
Micro Business Credit in India: Gujarat’s Growing Lending Market
Gujarat’s Micro-Business Credit Crosses ₹2.41 Lakh Crore as Individual Borrowing Grows Faster
Nearly 25 lakh entrepreneurs have yet to take business loans in an enterprise’s name, despite many having strong personal credit records
Gujarat’s micro-business credit market reached ₹2.41 lakh crore in outstanding loans in June 2026, with individual entrepreneurs borrowing for business purposes at a faster rate than registered business entities.
Outstanding loans to individual business borrowers grew at an annual rate of 18% over three years, while credit to micro businesses rose by 13%, according to a study by TransUnion CIBIL and the National Small Industries Corporation (NSIC).
The figures point to a growing gap in how small businesses access money. Many entrepreneurs already have personal borrowing records, yet have not taken loans in the name of their businesses.
In Gujarat, around 24.8 lakh individual entrepreneurs had never borrowed as enterprises by March 2026. Of these, 72% had a CIBIL Credit Score above 730, a score that indicates a strong record of managing personal credit.
The findings raise questions about how lenders assess small businesses and whether entrepreneurs can obtain loans that match their business needs.
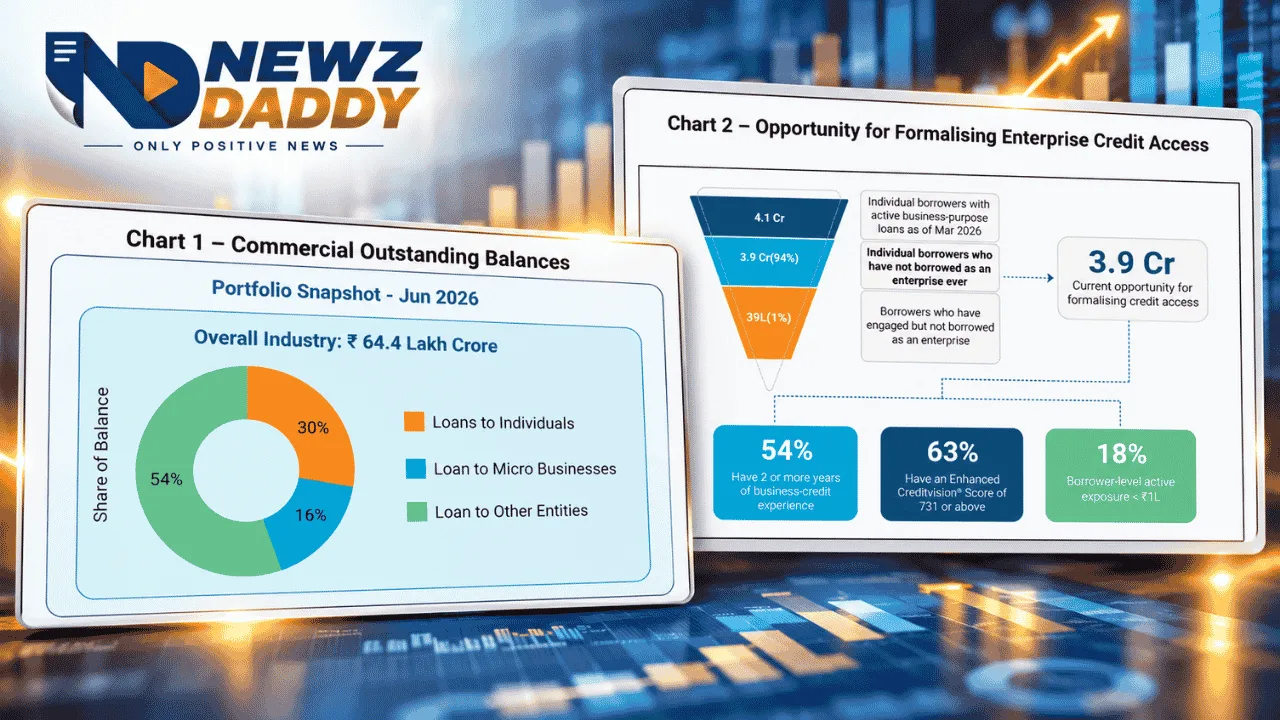
The study, titled Micro Business Entrepreneurs in India: Growth, Transformation & Emerging Opportunities, puts India’s outstanding micro-business entrepreneur (MBE) credit at ₹29.6 lakh crore in June 2026. This accounted for nearly half of the country’s commercial credit portfolio.
Of this amount, ₹19.1 lakh crore was held by individuals borrowing for business purposes, while ₹10.5 lakh crore belonged to micro businesses. Individual business borrowing grew at a 21% compound annual growth rate (CAGR) over three years. Credit to micro businesses grew at 12%.
The figures show that individual entrepreneurs are taking a larger share of business loans. They also point to the need for lenders to understand how personal borrowing supports business activity.
Gujarat’s industrial base helps explain the demand for business credit. Manufacturing accounted for 36% of outstanding balances among micro businesses in the state. Textile industry credit grew at an 18% CAGR over three years.
Loans Against Property (LAP) remained the largest lending product, accounting for 38% of MBE balances. Cash credit, overdraft facilities and commercial vehicle loans also supported businesses.
Private sector banks held nearly 45% of individual business borrower balances. Non-bank finance companies (NBFCs) continued to play an important role in commercial vehicle financing.
For a textile unit, a loan may help pay for machinery or raw materials. A trader may need money to buy stock before sales begin. A transport operator may need funds to purchase a vehicle. Each business has different needs and repayment patterns.
Mr Bhavesh Jain, MD and CEO of TransUnion CIBIL, said: “Gujarat’s entrepreneurial ecosystem has a strong manufacturing and trading base, with businesses at different stages of growth requiring different forms of financing. A textile manufacturer investing in capacity, a trader managing inventory, and an entrepreneur looking to expand operations have distinct credit requirements. As these businesses grow, lenders have an opportunity to look more closely at their operating cycles, existing credit histories and future financing needs. Helping entrepreneurs build credit relationships in their enterprise capacity can improve their access to suitable financial products and support the next stage of business expansion.”
The study found a similar gap across India. Around 3.9 crore individual business borrowers had never taken loans in an enterprise’s name by March 2026. Of these, 54% had at least two years of business-credit experience as individuals. Another 63% had a CIBIL Score above 730.
For lenders, these borrowers may be candidates for business loans, depending on their income, repayment ability, business records and the lender’s rules.
Enterprise-level borrowing can help businesses build a credit history in their own name. It may also give them access to products such as cash credit and overdrafts, which help meet daily expenses and working capital needs.
Gujarat’s credit records offer further information about borrowers. As of June 2026, 62% of outstanding balances among individual business borrowers belonged to the above-prime segment, the highest share among the major states studied.
The state’s 90-plus-day delinquency rate, which measures loans with payments overdue by more than 90 days, fell by about 45 basis points over three years to 1.2%.
At the national level, the study found that lending remained heavily linked to property and other assets. Loans Against Property accounted for ₹10.9 lakh crore in outstanding balances in June 2026. Cash credit and overdraft facilities stood at ₹5.6 lakh crore, while commercial vehicle loans accounted for ₹5 lakh crore.
These figures show why collateral remains important when small businesses seek loans. A business owner who does not own property may find it harder to obtain funding, even with a good personal credit record.
The government’s Credit Guarantee Scheme, run through the Credit Guarantee Fund Trust for Micro and Small Enterprises (CGTMSE), offers guarantees to lenders for eligible loans to micro and small businesses. The scheme supports collateral-free and third-party guarantee-free credit. Its guarantee ceiling for banks was raised from ₹5 crore to ₹10 crore for loans approved from 1 April 2025.
Such schemes can help lenders take on some of the risk of lending to smaller businesses. However, borrowers must still meet the lender’s eligibility and repayment requirements.
India’s commercial credit portfolio also showed better repayment performance. Overall delinquency fell from around 3% in June 2023 to 1.9% in June 2026, according to the study.
The improvement comes as business credit continues to grow. Yet lenders must assess risks carefully, especially when offering unsecured loans to businesses with limited records.
For entrepreneurs, the figures underline the need to keep business accounts, record sales and expenses, and repay loans on time. These records can help lenders judge how much a business can borrow and how it may repay the money.
The next stage of micro-business lending will depend partly on whether banks and finance companies can assess business income and cash flow alongside property and other security. Better access to enterprise-level credit could help eligible entrepreneurs move away from relying only on personal loans to fund their businesses.
For Gujarat’s millions of small business owners, the question is whether their existing credit history can help them obtain the right loan in the name of their business.